What are T-Accounts? A Beginner’s Guide with Examples
All articles
A T-account is a simple way to show an account in double-entry bookkeeping: debits on the left, credits on the right, under the account name. It gets its name because it looks like the letter T.
T-accounts are a key tool in double-entry bookkeeping, helping accountants picture their transactions in different accounts. In this guide, we’ll break down what T-accounts are, how they work and how they fit into modern accounting.
What is a T-account?
A T-account is a visual representation of an account used in double-entry bookkeeping. It’s called a “T” account because its format resembles the letter T, with debits on the left and credits on the right.
Any transaction a business makes will need to be recorded in the company’s general ledger. The general ledger is divided up into individual accounts which categorise similar transaction types together.
Here is the basic format, using a cash account:
| Debit (left) | Credit (right) |
|---|---|
| Sales received £500 | Rent paid £300 |
| Balance £200 |
Why do accountants use T-accounts?
T-accounts serve as a simple yet powerful tool for tracking transactions in double-entry accounting. Accountants use them because they offer:
- Clear organisation: T-accounts visually separate debits and credits, making it easier to spot errors.
- A structured audit trail: By recording every transaction in a systematic way, T-accounts help accountants and auditors trace financial movements.
- Better financial insights: When used alongside ledgers and financial statements, T-accounts help businesses track patterns in expenses and revenue.
While modern accounting software automates much of this process, understanding T-accounts is still fundamental for accountants and finance professionals.
T-accounts are a visual way of checking journal entries before they are posted.
T-Account example chart

A T-account has three sections. The top is the name of the account. The left-hand side is where you enter debits, while the right-hand side is where you enter credits. Understanding the difference between credit and debit is essential for this process.
How do T-accounts work?
T-accounts help to visualise the accounting process, showing a clear picture as to what is occurring with each transaction. They are a useful tool for newcomer and veteran accountants alike to quickly map out the correct way to record a transaction.
Complex entries might have impacts in multiple accounts. By breaking transactions down into a simple, digestible form, you can visualise which accounts are being debited and which are being credited.

In this image, you can see a T-account which shows a café business’s bank account for the first week of March. The cash received from coffee sales is shown in the debit column on the left, while the credits (operating costs) are shown on the right.
Below is a simplified view of the full ledger account. When these transactions are posted to the company’s accounts, they will be displayed with more information:
| Cash Account | ||||
|---|---|---|---|---|
| Date | Description | Debit | Credit | Balance |
| 01/03/2025 | Opening Balance | £1,000.00 | £1,000.00 | |
| 01/03/2025 | Sales | £310.50 | £1,310.50 | |
| 02/03/2025 | Sales | £290.10 | £1,600.60 | |
| 02/03/2025 | Inventory | £30.10 | £1,570.50 | |
| 03/03/2025 | Sales | £314.80 | £1,885.30 | |
| 04/03/2025 | Sales | £306.80 | £2,192.10 | |
| 04/03/2025 | Inventory | £42.70 | £2,149.40 | |
| 05/03/2025 | Sales | £297.40 | £2,446.80 | |
| 05/03/2025 | Operating Cost | £300.00 | £2,146.80 |
A T-account is a quick way to work out where debits and credits go before they are recorded in full, which helps avoid data entry errors. It lacks the detail of the ledger, but it shows the key information.
Which side increases an account depends on its normal balance.
Advantages of using T-accounts
T-accounts are more than a learning tool: they play a key role in helping businesses and accountants keep accurate financial records. Here’s why they’re valuable:
1. Simplifies transaction tracking
T-accounts break down transactions into clear debit and credit entries, making it easier to follow the movement of money.
2. Acts as a troubleshooting tool
When books don’t balance, T-accounts provide a structured way to identify where errors might have occurred.
3. Enhances financial transparency
By visually separating different accounts, T-accounts help businesses and auditors understand financial flows at a glance.
4. Reinforces double-entry accounting
Every transaction is recorded in at least two places, reducing the likelihood of missing entries.
While many businesses rely on accounting software today, understanding T-accounts remains essential for financial accuracy and decision-making.
Read more about double-entry bookkeeping.
Examples of T-Accounts
Here are some examples from a café to show how T-accounts work.
Example 1: Selling a coffee
A cup of coffee is sold for £2.50. What happens in the accounts?

As you can see, the bank account is debited £2.50, increasing its value. The income account (revenue account) is being credited £2.50, increasing its value and making the transaction balanced.
However, the business will use some inventory when making the coffee:

The ingredients for the cup of coffee are recorded as inventory (asset account). They come from the business’s store cupboard. Inventory is reduced each time a cup of coffee is sold, so the business needs to credit the inventory account by 50p, reducing its value. This is a double-entry, and the accounts are balanced.
Example 2: Purchasing a coffee machine
The coffee shop has purchased another coffee machine for £700. However, it decides to pay for the machine the following month. So, what happens to the accounts?

As the business has received the coffee machine, it has gained £700 worth of fixed assets (this account has been debited).
As the business will be paying for the coffee machine in the following month, the accounts payable is increased (credited) by £700.

In the next month, the business’s bank account is credited £700 (reducing its value) as the business has now paid for the coffee machine.
With the outstanding bill paid, accounts payable account is debited by £700, reducing its value and showing that there is no more money owed.
Example 3: Paying rent
The business needs to pay £2,000 for renting the unit for the coffee shop. So, what happens to the accounts?

Rent is classed as an operating cost, as it is a standard cost of running the business. Operating costs are a type of expense, so the rent account is debited by £2,000.
To pay the rent, the business has used cash, so the bank account (an asset account) is credited by £2,000.
Now say the next month comes and the business can’t afford to pay the rent. It agrees with the landlord to pay it the following month, along with that month’s rent.
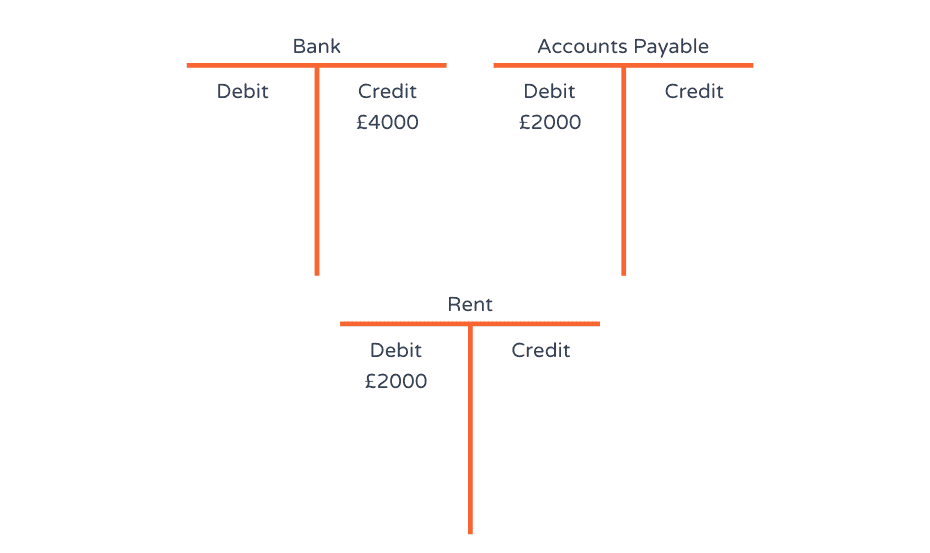
As the business owes both this month’s and last month’s rent, it pays £4,000. The bank account is credited £4,000, while the accounts payable account is debited £2,000 and rent is debited £2,000. So the debits and credits in this transaction are equal.
Example 4: Rent prepaid for a quarter
In this example, the business decides to pay rent for the next quarter in advance.
In January, it pays £6,000 in cash to the landlord, so the bank (asset) account is credited £6,000.

With three months of rent paid for, the prepayments (prepaid rent) account is debited £6,000.
Prepayments is an asset account on the balance sheet. The prepaid £6,000 is an asset because the rent has been paid in advance: the landlord owes the business three months’ use of the property.
Each month, £2,000 is credited to this account as the rent is used up.

The £2,000 credit each month to the prepayment account is balanced by the £2,000 debit to the rent expense account:

Example 5: Buying stock on credit and paying the supplier
The café buys £400 of coffee beans on credit. Its stock goes up (debit Stock £400) and it now owes the supplier (credit Accounts payable £400). A month later it pays the supplier: debit Accounts payable £400, which clears the debt, and credit Cash £400.
| Accounts payable: Debit | Accounts payable: Credit |
|---|---|
| Supplier paid £400 | Stock bought on credit £400 |
| Balance £0 |
See how accounts payable and receivable affect cash flow.
Free printable T-account template
Copy or print this blank T-account to practise your own entries:
| Account name: ____________ | |
|---|---|
| Debit | Credit |
| Balance: | Balance: |
Common mistakes when using T-accounts
T-accounts are a great way to visualise accounting transactions, but mistakes can still happen. Here are some common pitfalls:
- Misplacing debits and credits: A simple reversal can throw off the entire balance of an account.
- Forgetting adjusting entries: Without proper adjustments, financial reports may not reflect accurate balances.
- Omitting transactions: If a transaction isn’t recorded in the T-Account, it won’t appear in the ledger or financial statements.
- Not balancing accounts: Each T-Account should eventually balance; if not, an error might exist in the double-entry system.
By double-checking entries and reconciling accounts regularly, businesses can avoid costly accounting errors.
Problems with T-accounts
While T-accounts offer many benefits, they also come with some limitations, especially in modern accounting:
1. Time-consuming for complex businesses
Manually maintaining T-accounts for every transaction can be impractical for large organisations with thousands of entries.
2. Prone to human error
If transactions are recorded incorrectly in a T-account, the mistake carries over to financial reports.
3. Limited real-world use
Businesses don’t typically use T-accounts for daily operations. Instead, ledgers and automated systems handle transaction tracking.
4. Requires double-checking
Because T-accounts rely on manual input, they need careful review to ensure accuracy.
Despite these challenges, T-accounts remain an essential learning tool and a useful way to visualise complex accounting concepts.
Manage your T-accounting in Brixx
When learning the accounting process, from debits and credits to double-entry, it’s easy to get lost in the process and miss the big picture.
Whether you are an accountant or a decision-maker, the language of business finance is rooted in accounting, so it’s worth grasping the basics. Every transaction a company makes, whether it’s selling coffee, taking out a loan or buying an asset, has a debit and a credit. This means every financial event is recorded and can be accurately represented in financial reports.
The key financial reports (your cash flow, profit and loss and balance sheet) are an organised representation of these fundamental accounting records. They are built from the ground up by these debits and credits. It’s these reports that you’ll be analysing to aid your decision-making process.
Your profit and loss organises your revenue and expense accounts whilst your balance sheet organises your asset, liability and equity accounts. The double entry process connects these reports together. A single transaction will have impacts across all reports due to the way debits and credits work. So grasping these basics helps you delve into these reports and understand the financial story they tell.
Brixx, our financial forecasting software, helps you with this process further. The software handles all the accounting work. When you enter any forecast activity, the double-entry process is completed for you, saving you time and giving you confidence in the numbers. It means you can spend more time analysing the results. Get started today with a free 7-day trial.
Plan your cash flow in Brixx
Easy to use forecasting software so you can plan for your business's financial future
Start your free trialYou might also like our free balance sheet template.
Frequently asked questions
What is a T-account?
A T-account is a simple way of showing one account in double-entry bookkeeping, with debits on the left and credits on the right.
Which side of a T-account is the debit?
The left side. Credits go on the right.
How do you balance a T-account?
Add up each side, take the smaller total from the larger, and enter the difference as the balance. If the debit side is bigger, the account has a debit balance; if the credit side is bigger, it has a credit balance.
Do accountants still use T-accounts?
Rarely for day-to-day bookkeeping, which is done in software, but they are widely used for teaching, planning tricky entries and tracking down errors.
What is a T-chart in accounting?
A T-chart is another name for a T-account.